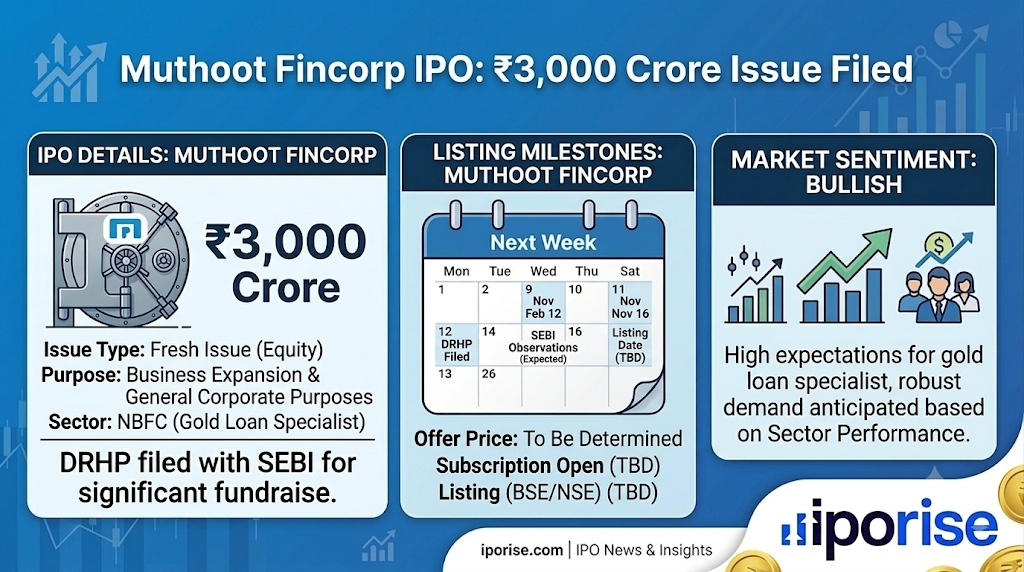
Muthoot Fincorp, the gold loan NBFC from the Muthoot Pappachan Group, has filed its DRHP with SEBI to raise ₹3,000 crore entirely through a fresh issue. With profit tripling in FY26 and AUM crossing ₹73,000 crore, the company is now ready for its public market debut.
One of India's oldest and most recognised names in gold lending is finally heading to the stock market. Muthoot Fincorp, the flagship NBFC of the Muthoot Pappachan Group, filed its Draft Red Herring Prospectus with SEBI on August 12, 2026, to raise ₹3,000 crore through an IPO.
Unlike many public offerings, this IPO has no offer-for-sale component the entire ₹3,000 crore will come through a fresh issue of equity shares. That means all the money raised goes directly into the business, not to exiting shareholders a detail retail investors usually appreciate.
What Will the Money Be Used For?
The proceeds will be used to strengthen the company's Tier-I capital base to meet future capital requirements, including funding onward lending and supporting the growth and expansion of its business. A chunk of this will also go toward scaling its digital platform, Muthoot FinCorp ONE, and growing its diversified lending portfolio beyond gold loans.
A Business Built Over Eight Decades
Muthoot Fincorp has evolved over 86 years since it co-founded a gold loan business in 1939 as part of the group's heritage trading business, while the Muthoot Pappachan Group itself traces its roots back to 1887. That kind of legacy is hard to replicate and it shows in the trust the brand commands across rural and semi-urban India.
The company is a diversified NBFC with gold loans as its flagship product, but its portfolio also spans business loans, loans against property, supply chain financing, digital loans, microfinance, and housing loans. It also distributes insurance and payments products through its branch network.
Scale That's Hard to Ignore
As of March 31, 2026, Muthoot Fincorp had an AUM of ₹73,444 crore, a pan-India branch network of 5,610 branches, and a growing digital user base of 4.26 million customers. Over the last three financial years, it served over 8.22 million unique customers.
The growth in its gold loan book has been particularly sharp. Its gold loan AUM grew at a CAGR of 59.04% between March 2024 and March 2026 the fastest among its peers during the period, according to a CRISIL report cited in the DRHP. That's a remarkable clip for a business of this size.
Financials Tell a Strong Story
The numbers back up the confidence. Consolidated revenue from operations jumped to ₹11,203 crore in FY26 from ₹8,497 crore in FY25. Net profit more than tripled from ₹607 crore in FY25 to ₹1,847 crore in FY26. Profit nearly tripling in a single year is a number that will get investors' attention.
Who's Managing the IPO
Kotak Mahindra Capital, Morgan Stanley India, JM Financial, and SBI Capital Markets are the book-running lead managers for the issue. A strong banker lineup for what could be one of the larger NBFC IPOs of FY27.
The listing exchange and timeline have not been announced yet, and the company is awaiting SEBI observations before finalising pricing and dates.