Muthoot FinCorp's board has cleared a Rs 4,000 crore IPO, all of it a fresh issue, along with a 1:5 stock split and a Rs 8,000 crore debt fundraise. Here is the full breakdown
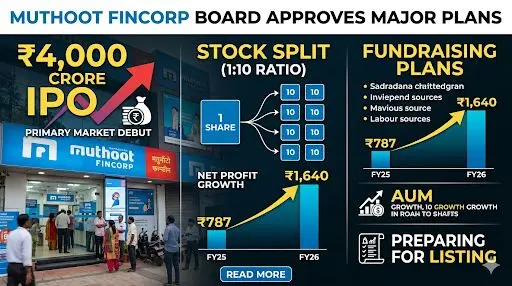
Muthoot FinCorp, the flagship NBFC of the Muthoot Pappachan Group, has cleared its board's approval for an IPO of up to Rs 4,000 crore. The decision came in a board meeting on Saturday, May 16, 2026, and the issue will be entirely a fresh issue of equity shares with a face value of Rs 10 each. There is no offer for sale component.
Muthoot FinCorp, the flagship NBFC of the Muthoot Pappachan Group, has received its board's approval for an IPO of up to Rs 4,000 crore. The decision came in a board meeting on Saturday, May 16, 2026. The issue will be entirely a fresh issue of equity shares with a face value of Rs 10 each. There is no offer for sale component.
This is one of the larger NBFC IPO proposals in the 2026 pipeline, and it comes bundled with a stock split and an aggressive debt fundraising plan worth flagging in full.
Quick note: Muthoot FinCorp is not Muthoot Finance
This trips up investors constantly, so worth clearing up first. Muthoot Finance (already listed, market cap around Rs 1.6 lakh crore) is the flagship of the Muthoot Group, promoted by the M. George branch of the family. Muthoot FinCorp is part of the Muthoot Pappachan Group, promoted by the Pappachan branch. Same family origin in Kerala, separate companies, no cross-shareholding. The IPO under discussion is for FinCorp, not Finance.
What the board cleared
The May 16 meeting approved a full slate of fundraising items:
- IPO of up to Rs 4,000 crore: 100 percent fresh issue, face value Rs 10 per share. Subject to shareholder approval, regulatory clearances and market conditions.
- Stock split (1:5): Each existing Rs 10 face value share to be subdivided into five shares of Rs 2 face value each.
- Public NCD issuance of up to Rs 4,000 crore: Window of July 1, 2026 to June 30, 2027.
- Private placement of debt up to Rs 4,000 crore: Includes NCDs, perpetual debt instruments and subordinated debt.
- Commercial paper programme of Rs 30,000 crore overall: Maximum outstanding capped at Rs 10,000 crore.
The debt portion alone is twice the size of the IPO, which tells you the company expects to keep funding growth largely through borrowing rather than equity.
Why the stock split matters
A 1:5 split is meaningful in the IPO context. Post-split, each share will have a face value of Rs 2 instead of Rs 10. This brings the per-share IPO price band lower, which makes the issue more accessible to retail investors and tends to improve secondary market liquidity after listing. It also puts FinCorp in line with how most mid-cap NBFC listings are structured.
The financial backdrop
The proposal comes off a strong FY26.
Consolidated numbers (FinCorp plus subsidiaries Muthoot Microfin and Muthoot Housing Finance):
- Net profit for FY26: Rs 1,847.62 crore, up 204 percent from Rs 608 crore in FY25.
Standalone Muthoot FinCorp, as of March 2026:
- Assets under management: Rs 56,185.10 crore
- Profit after tax: Rs 1,640.21 crore
- Revenue: Rs 8,364.28 crore
The 204 percent profit jump is the headline, but read it carefully. NBFC profits can swing year-on-year on credit cost write-backs, gold price movements (FinCorp is heavily into gold loans), and provisioning policy. The DRHP segment-wise breakup will give a cleaner read.
Gold loan NBFCs have had a strong run through 2025 and FY26. Gold prices have stayed at elevated levels, which directly lifts the loan-to-value ceiling and lets companies grow AUM without taking more credit risk per loan. Muthoot Finance is trading near record highs. Manappuram Finance has seen its valuation rerate. For the Pappachan Group, this is as good a listing window as they are likely to get.
There is a group strategy angle too. Muthoot Microfin listed in late 2023. Taking the parent NBFC public completes the group's listed footprint and creates a cleaner valuation benchmark for the unlisted holdings.
What we still do not know
The board approval is just step one. The pending pieces:
- DRHP filing date with SEBI. No timeline confirmed.
- Price band and final issue size, to be set closer to issue date.
- Lead managers and registrar. Not yet announced.
- Use-of-proceeds breakup. For a fresh-issue-only IPO, this is the single most important disclosure to read carefully. Most NBFC IPOs deploy a chunk of proceeds to augment Tier-I capital and the rest for general corporate purposes.